Open a Free Demat Account !
₹0 AMC & Account Opening Fee
Bonfiglioli Transmissions IPO Review: Good or Bad?

 Last Updated: 15 October, 2026
 21 min read



00:00 / 00:00


Quick summary
| ||
Is the Bonfiglioli Transmissions IPO good or bad? Going by the numbers, it is a profitable company with no borrowings, rising margins and a leading share in the gearbox and wind-drive niches it serves. It also depends on its Italian parent for its brand, technology licence and a large part of its sales and costs, and the parent is the only seller, so the company gets no money from the issue. Whether that trade-off suits you depends on how much risk you can carry, so this article lays out the evidence instead of a one-word verdict.
We read the Red Herring Prospectus (RHP) of Bonfiglioli Transmissions Limited, dated 9 October 2026, and pulled the figures that matter for an investor. Every number below comes from it unless we name another source. The company's financial year here ends on 31 December, so FY25 means the year to 31 December 2025. If the document is new to you, our guide to the red herring prospectus explains each section.
Investments in the securities market are subject to market risks. Read all the related documents carefully before investing. This article is for education and is not investment advice.
Bonfiglioli Transmissions IPO Details
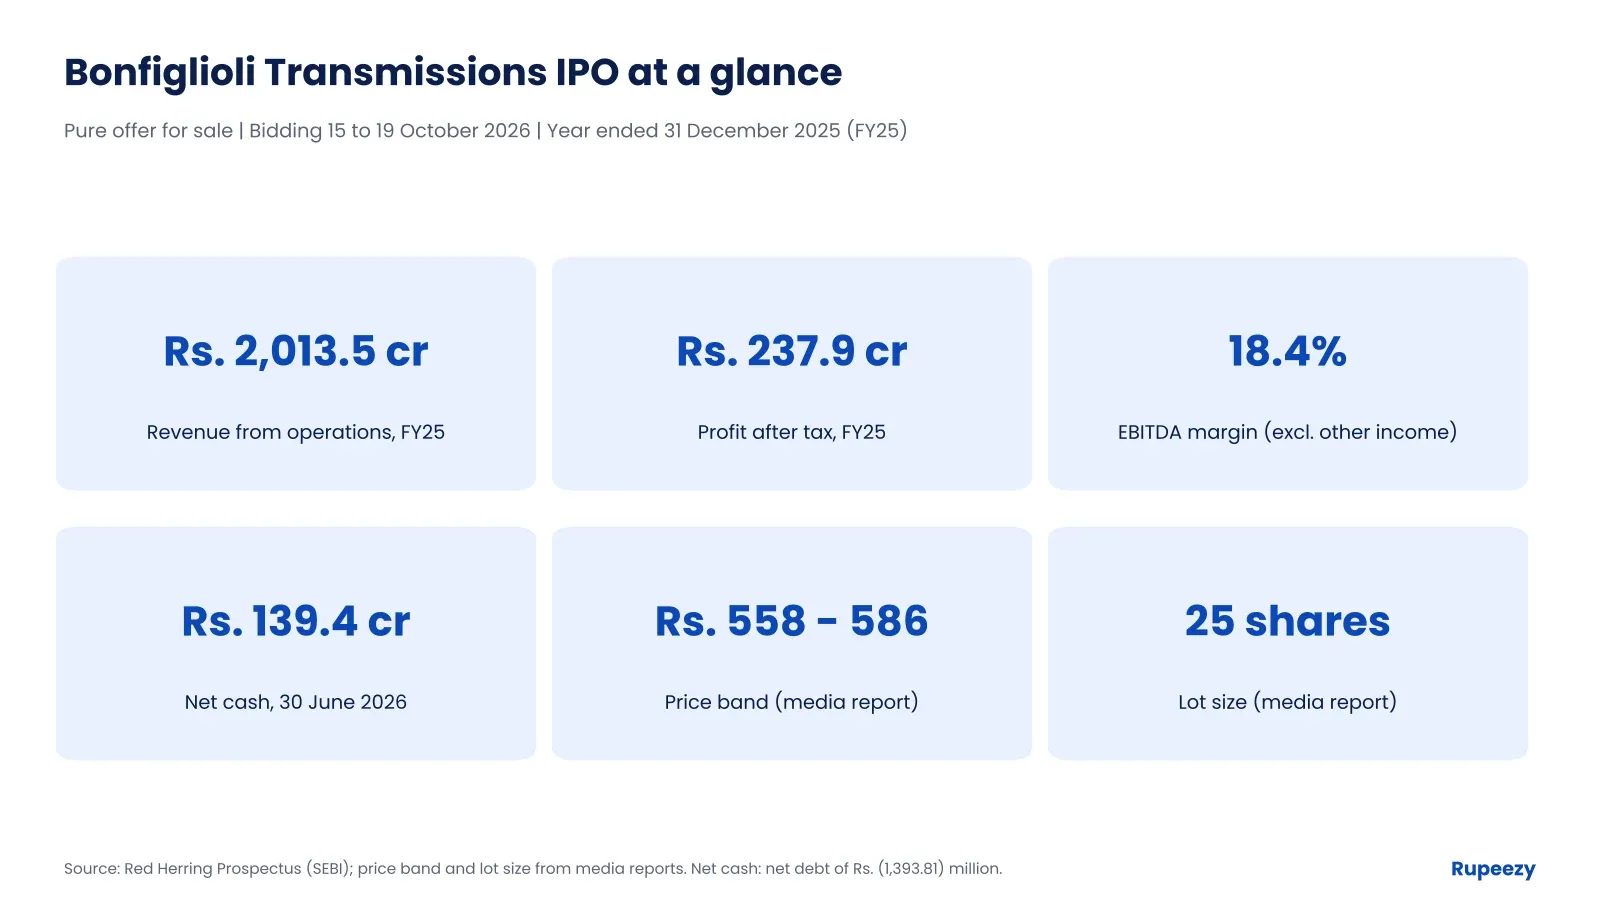
Here are the terms you need before you bid. The bidding dates, share count and quota come from the RHP. The RHP leaves the price band and lot size blank, because they are announced in a newspaper advertisement at least two working days before the issue opens, so we took them from media reports of the company's announcement. Check them against the final price band advertisement and your bid form.
Detail | Bonfiglioli Transmissions IPO |
Issue type | Book-built; 100% offer for sale (Regulation 6(1) of SEBI ICDR) |
Fresh issue | None |
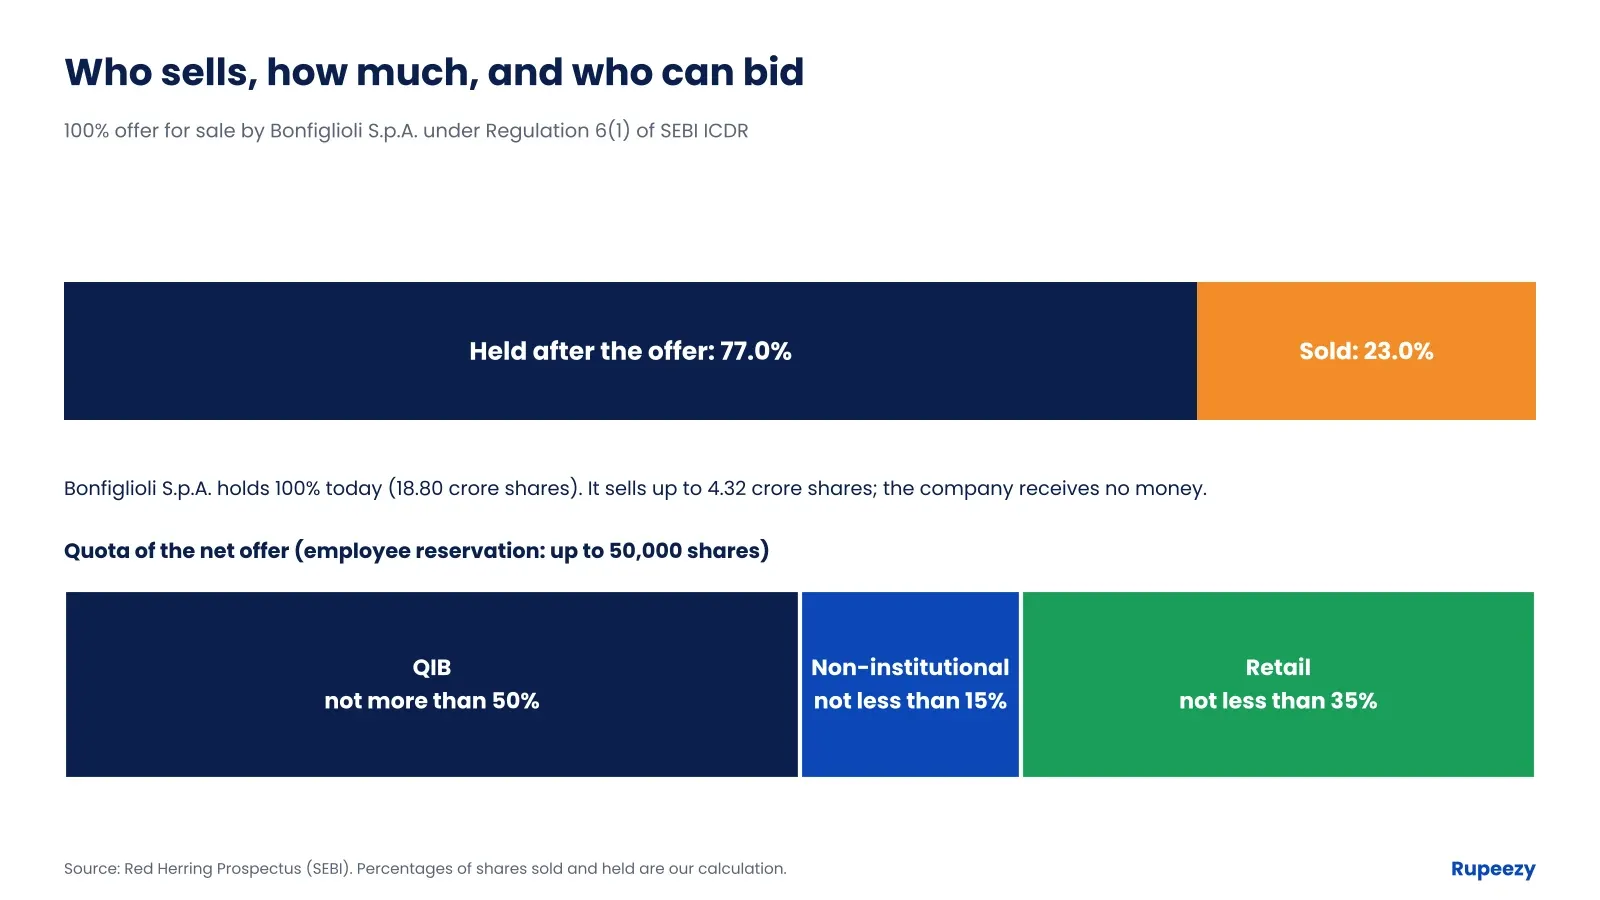
Offer for sale | Up to 4,32,39,042 equity shares of face value Rs. 10, all by Bonfiglioli S.p.A. |
Share of company sold | 23.0% of the 18,79,95,834 shares outstanding (our calculation) |
Total issue size | About Rs. 2,413 crore at Rs. 558 and Rs. 2,534 crore at Rs. 586 (our calculation) |
Anchor bidding | 14 October 2026 |
Bidding opens / closes | 15 October 2026 / 19 October 2026; UPI mandate cut-off 5:00 pm on the last day |
Price band | Rs. 558 to Rs. 586 per share (media report) |
Lot size | 25 shares (media report) |
Minimum bid | Rs. 13,950 at Rs. 558; Rs. 14,650 at Rs. 586 (our calculation) |
Maximum for retail investors | 13 lots (325 shares), Rs. 1,90,450 at Rs. 586 (our calculation) |
Quota | QIBs not more than 50%; non-institutional investors not less than 15%; retail investors not less than 35% of the net offer |
Employee reservation | Up to 50,000 shares |
Registrar | MUFG Intime India Private Limited |
Lead managers | Axis Capital, BNP Paribas, ICICI Securities and Jefferies India |
The quota is the detail to notice. Under Regulation 6(1), retail investors are reserved at least 35% of the net offer and institutions at most 50%. That is a larger retail share than in loss-making IPOs filed under Regulation 6(2), where retail can be limited to 10%. A bigger quota does not guarantee allotment, which depends on how many people bid.
What Does Bonfiglioli Transmissions Do?
Bonfiglioli Transmissions makes gearboxes, gear motors and drive systems, the parts that turn a motor's fast spin into the slow, strong force a machine needs. It sells them to makers of factory equipment, construction machines and wind turbines. The Bonfiglioli brand is almost 70 years old worldwide, and the Indian company has been operating for more than 25 years. Its parent, Bonfiglioli S.p.A. of Italy, reports group revenue of Euro 1,172.94 million for 2025 across 18 production sites and more than 5,000 employees.
The business has three parts:
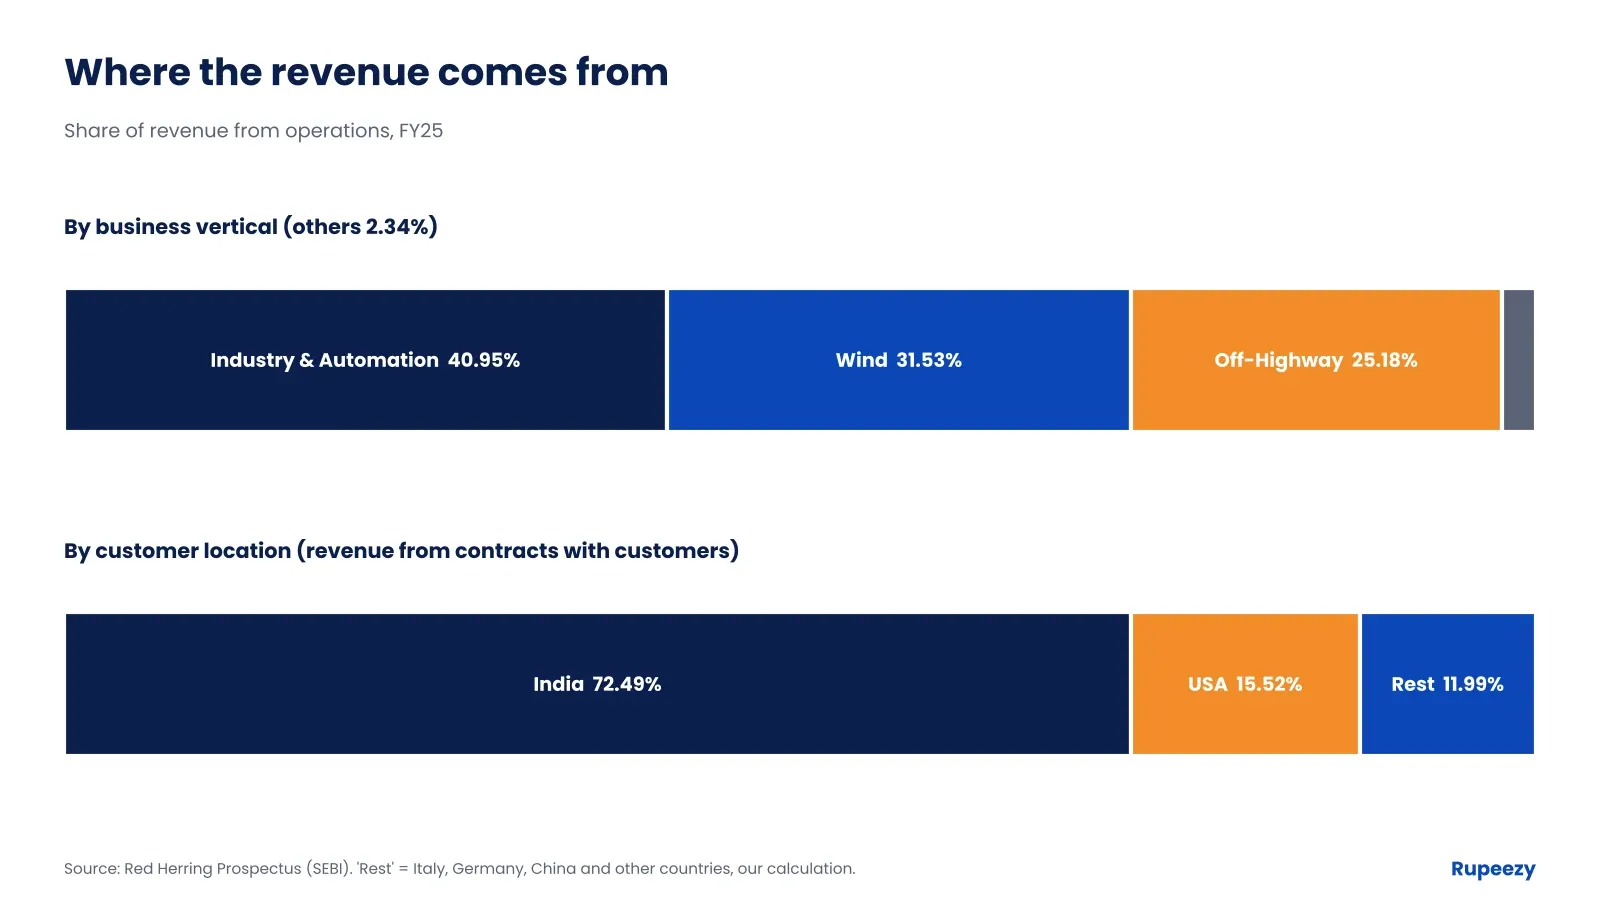
Industry and Automation: Gearboxes and motors for material handling, mining, food, plastics and similar equipment, sold directly and through 44 dealers. It gave 40.95% of FY25 revenue.
Wind: Yaw and pitch drives, which turn a turbine's blades and nacelle toward the wind. Customers include Suzlon, Nordex and Senvion. It gave 31.53% of FY25 revenue.
Off-Highway Mobility: Swing and track drives for excavators, cranes, road rollers and farm machines. Customers include JCB, Hyundai Construction Equipment and CNH. It gave 25.18% of FY25 revenue.
The RHP names the company as the largest maker in India of gear motors below 15 kNm for these industries, with a 25.0% share of that segment, 32.0% of off-highway drives among non-captive players and 67.9% of yaw and pitch drives among Indian makers. These claims come from a Frost & Sullivan report that the company commissioned and paid for, so treat them as the company's own case. The company runs three plants (two in Tamil Nadu and one at Talegaon in Maharashtra), has 1,032 employees and said its capacity use rose from 64.22% in FY23 to 73.71% in FY25 and 75.04% in the six months to June 2026.
By location, 72.49% of FY25 revenue from customers came from India and 15.52% from the USA. Dealers brought in 19.42% of total revenue, direct sales 63.30% and sales to other Bonfiglioli Group companies 15.22%.
Who Owns Bonfiglioli Transmissions and Who Is Selling?
Bonfiglioli S.p.A. holds 100% of the company (18,79,95,834 shares, including 10 held by its nominees) and none of those shares are pledged. It is selling up to 4,32,39,042 of them, which would leave it with about 77.0% after the issue (our calculation). The proceeds, roughly Rs. 2,413 crore to Rs. 2,534 crore at the reported band, go to the parent after offer expenses and taxes, and the company will not use this issue to build capacity, repay debt or fund working capital.
The parent has already been taking cash out. The company paid dividends of Rs. 65.56 crore in FY23, Rs. 46.37 crore in FY24 (plus a Rs. 72.00 crore share buyback) and Rs. 115.31 crore in FY25, and a further Rs. 109.98 crore in the six months to June 2026. That adds up to about Rs. 409 crore of dividends and buyback since January 2023 (our calculation). Even so, the company had no borrowings at June 2026 and held Rs. 140.17 crore in cash.
Bonfiglioli Transmissions Financials: Steady Growth, Rising Margins
All figures are restated numbers from continuing operations in Rs. crore, converted from the RHP's Rs. million figures. The two right-hand columns are six-month periods and are not annualised.
Metric (Rs. crore) | FY23 | FY24 | FY25 | Jan to Jun 2025 | Jan to Jun 2026 |
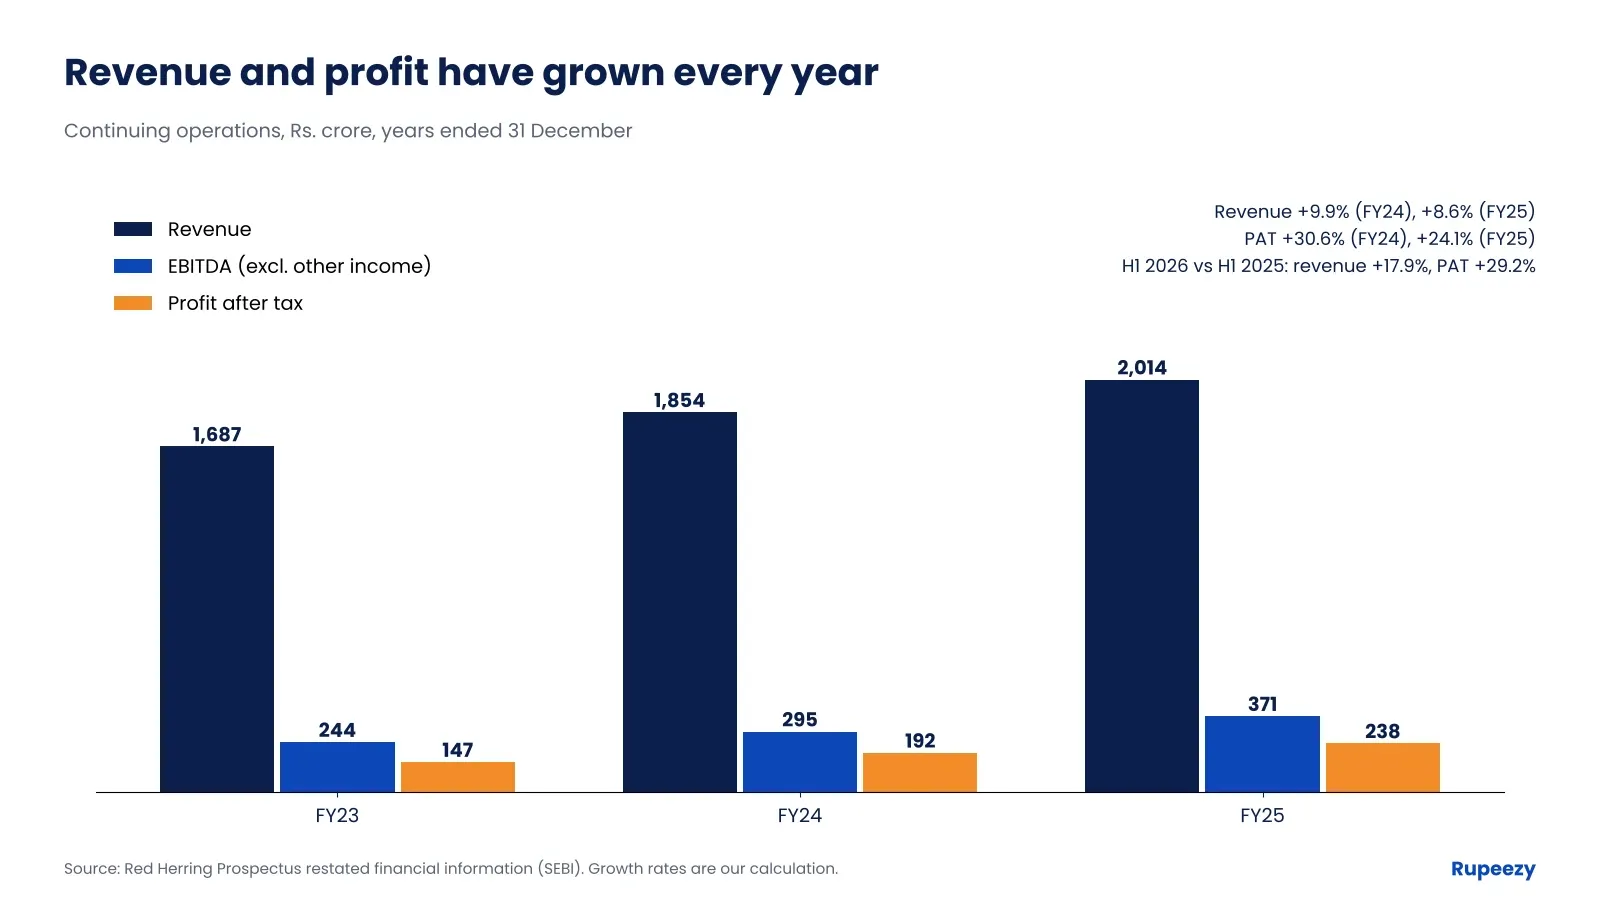
Revenue from operations | 1,687.33 | 1,854.18 | 2,013.53 | 960.36 | 1,131.87 |
Revenue growth | n/a | 9.89% | 8.59% | n/a | 17.86% (over Jan to Jun 2025) |
EBITDA (excl. other income) | 243.89 | 295.07 | 370.77 | 176.43 | 223.87 |
EBITDA margin | 14.45% | 15.91% | 18.41% | 18.37% | 19.78% |
Profit after tax | 146.67 | 191.60 | 237.87 | 114.97 | 148.58 |
PAT margin (on total income) | 8.62% | 10.29% | 11.76% | 11.90% | 13.04% |
Diluted EPS (Rs.) | 7.57 | 10.08 | 12.65 | 6.12 | 7.90 |
Return on equity | 19.21% | 23.05% | 25.66% | 13.24% | 14.66% |
Return on capital employed | 24.53% | 30.05% | 34.05% | 18.62% | 20.03% |
Total equity | 801.36 | 860.95 | 992.99 | 875.45 | 1,034.27 |
Net debt (negative = net cash) | -140.09 | -138.20 | -160.38 | -184.18 | -139.38 |
Three things stand out. First, profit has grown faster than revenue. EBITDA margin, which is operating profit before interest, depreciation and tax, rose from 14.45% in FY23 to 18.41% in FY25, and profit after tax rose 62.2% over the two years while revenue rose 19.3% (our calculation). Second, the company has not needed debt: it repaid its borrowings in FY24 and has held net cash every year since. Third, growth is not a straight line to count on. Revenue grew 9.9% and 8.6% in the last two full years, and the 17.9% jump in the first half of 2026 is a single six-month comparison.
EPS here is the figure the RHP restates after a 1-for-2 bonus issue in January 2026, so it is comparable across years. The weighted average EPS over FY23 to FY25 is Rs. 10.95 and the weighted average return on net worth is 22.45%. Note that FY24 profit after tax including a small discontinued business was Rs. 195.16 crore; we use the continuing figures throughout.
Cash Flow: Profit That Turns Into Cash
For a manufacturer that sells to other manufacturers, cash flow shows whether profit is real money or stuck in unpaid bills and stock.
Cash flow (Rs. crore) | FY23 | FY24 | FY25 | Jan to Jun 2026 |
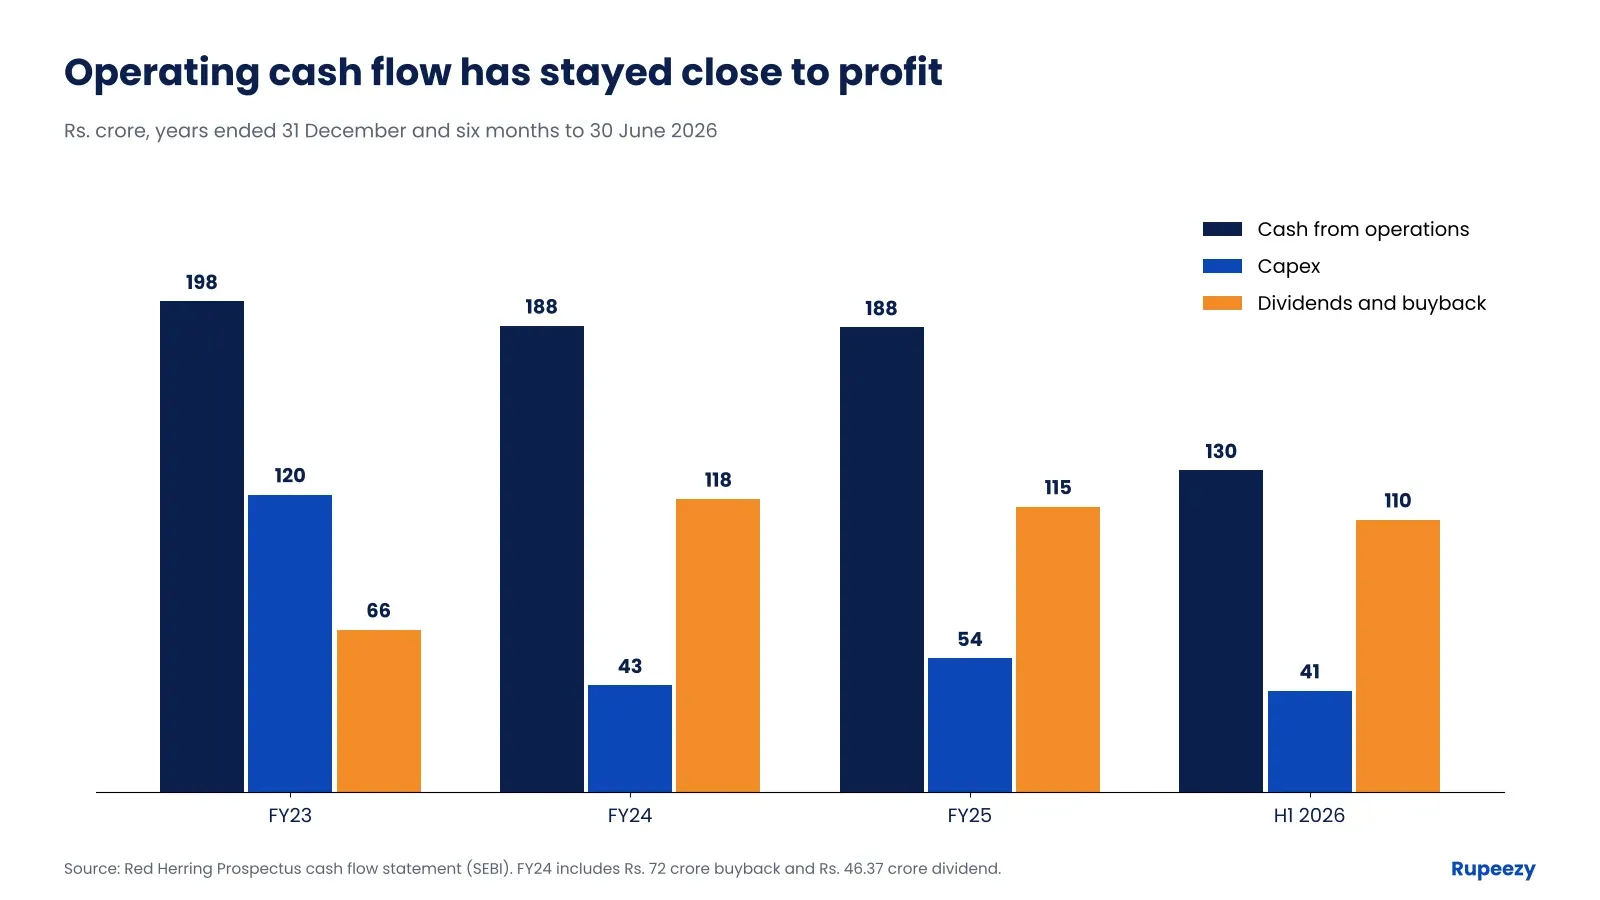
Cash from operations | 198.23 | 188.35 | 187.68 | 129.90 |
Capital spending | 120.12 | 43.08 | 53.98 | 40.92 |
Cash left after capex (our calculation) | 78.11 | 145.27 | 133.70 | 88.98 |
Dividends and buyback paid | 65.56 | 118.37 | 115.31 | 109.98 |
Cash and equivalents at year end | 90.53 | 144.67 | 153.18 | 140.17 |
Operations produced Rs. 187.68 crore of cash in FY25 against a profit of Rs. 237.87 crore, about 79% (our calculation), and Rs. 129.90 crore in the first half of 2026 against Rs. 148.58 crore of profit. The gap is working capital. The RHP's cash conversion cycle, the days it takes to turn stock and unpaid bills into cash after paying suppliers, has lengthened every year: 80 days in FY23, 83 in FY24, 90 in FY25 and 94 in June 2026. Trade receivables rose to Rs. 532.51 crore in June 2026 from Rs. 440.95 crore a year earlier, and inventories to Rs. 377.61 crore from Rs. 340.20 crore.
That is manageable while sales are growing, but it is the first number to watch if demand slows. The company also does not need the IPO for capex: it spent Rs. 40.92 crore in the first half of 2026 and funded it from its own cash.
The Parent Is Both Seller and Supplier
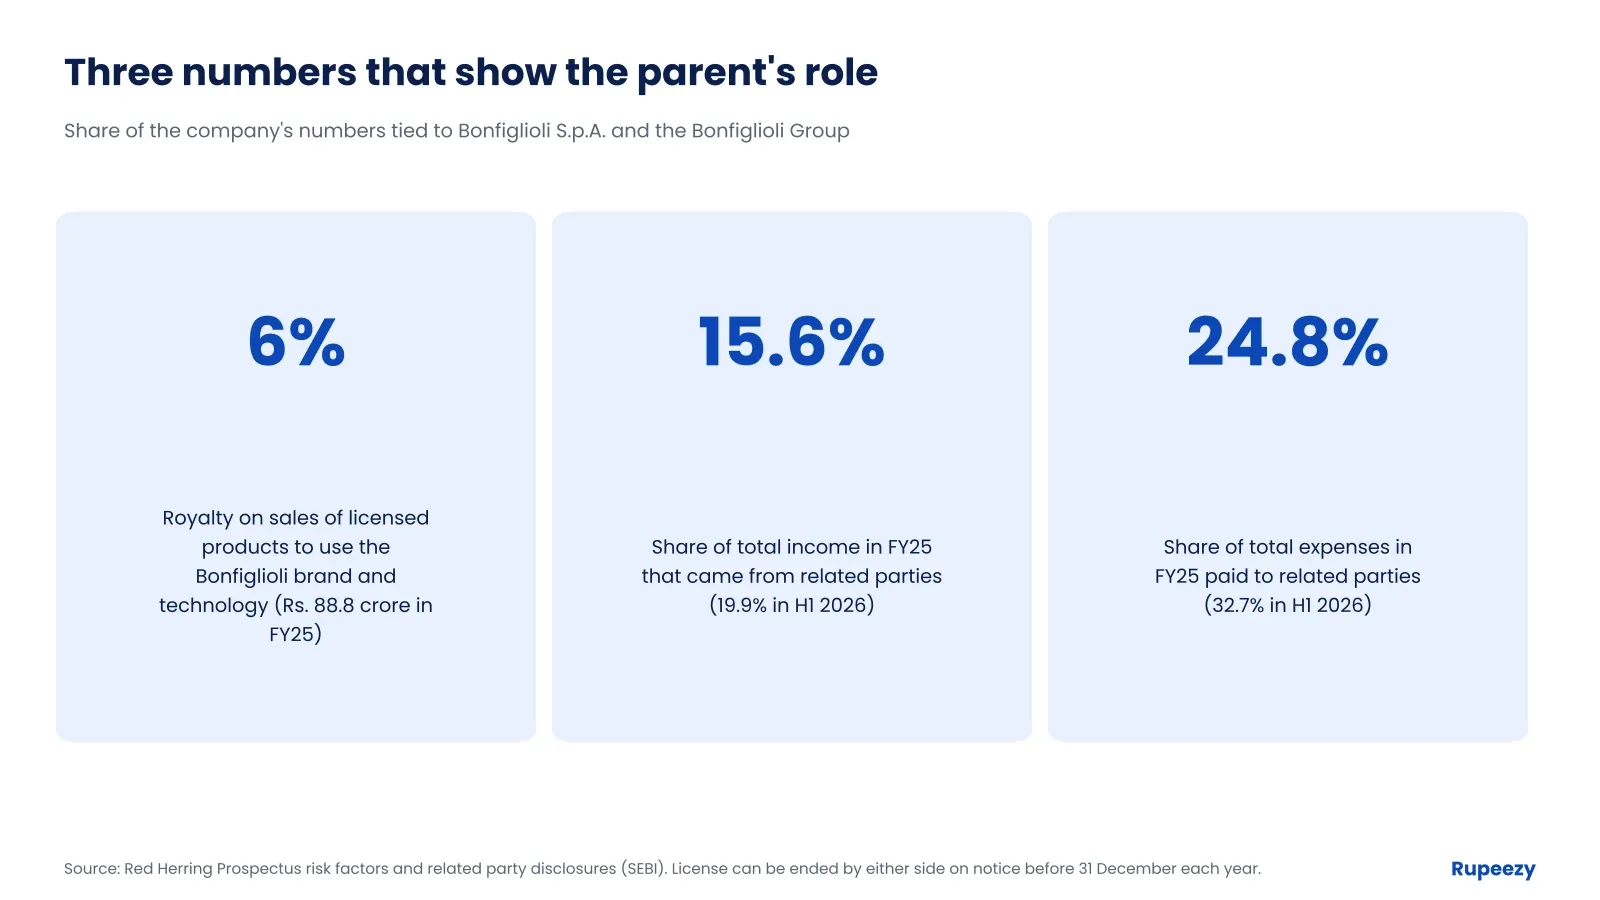
This is the part of the RHP that deserves the most attention. The company makes most of its products under a licence from Bonfiglioli S.p.A. that covers the brand, patents, drawings and know-how, for 6% of annual sales of the licensed products (excluding sales to the parent). That royalty was Rs. 88.81 crore in FY25, or 4.41% of revenue, and Rs. 50.54 crore in the first half of 2026. The licence is non-exclusive, runs for one year at a time and renews automatically, but either side can end it by giving notice before 31 December each year.
The parent also supplies corporate services such as IT, finance, HR and quality under a separate yearly agreement, and buys finished yaw and swing drives from the company. Together, related parties gave 15.59% of total income in FY25 (19.91% in the first half of 2026) and 24.83% of total expenses went to related parties (32.71%). The RHP says these dealings are on an arm's length basis. Still, a company that depends on its seller for its licence is in a different position from one with its own brand and technology.
Customers: Spread Out, With Wind as the Big Name
The company says it served more than 930 direct OEM customers in the first half of 2026. Its top 10 OEM customers gave 32.82% of revenue in FY23, 34.38% in FY24, 36.60% in FY25 and 31.72% in the first half of 2026, and its single largest customer gave 11.43% in FY25. That is far less concentrated than a business that depends on one or two buyers. Wind is the one segment to track: it gave 31.53% of FY25 revenue and depends on a small number of turbine makers, so a slowdown in wind orders would show up quickly.
Can You Judge the Price?
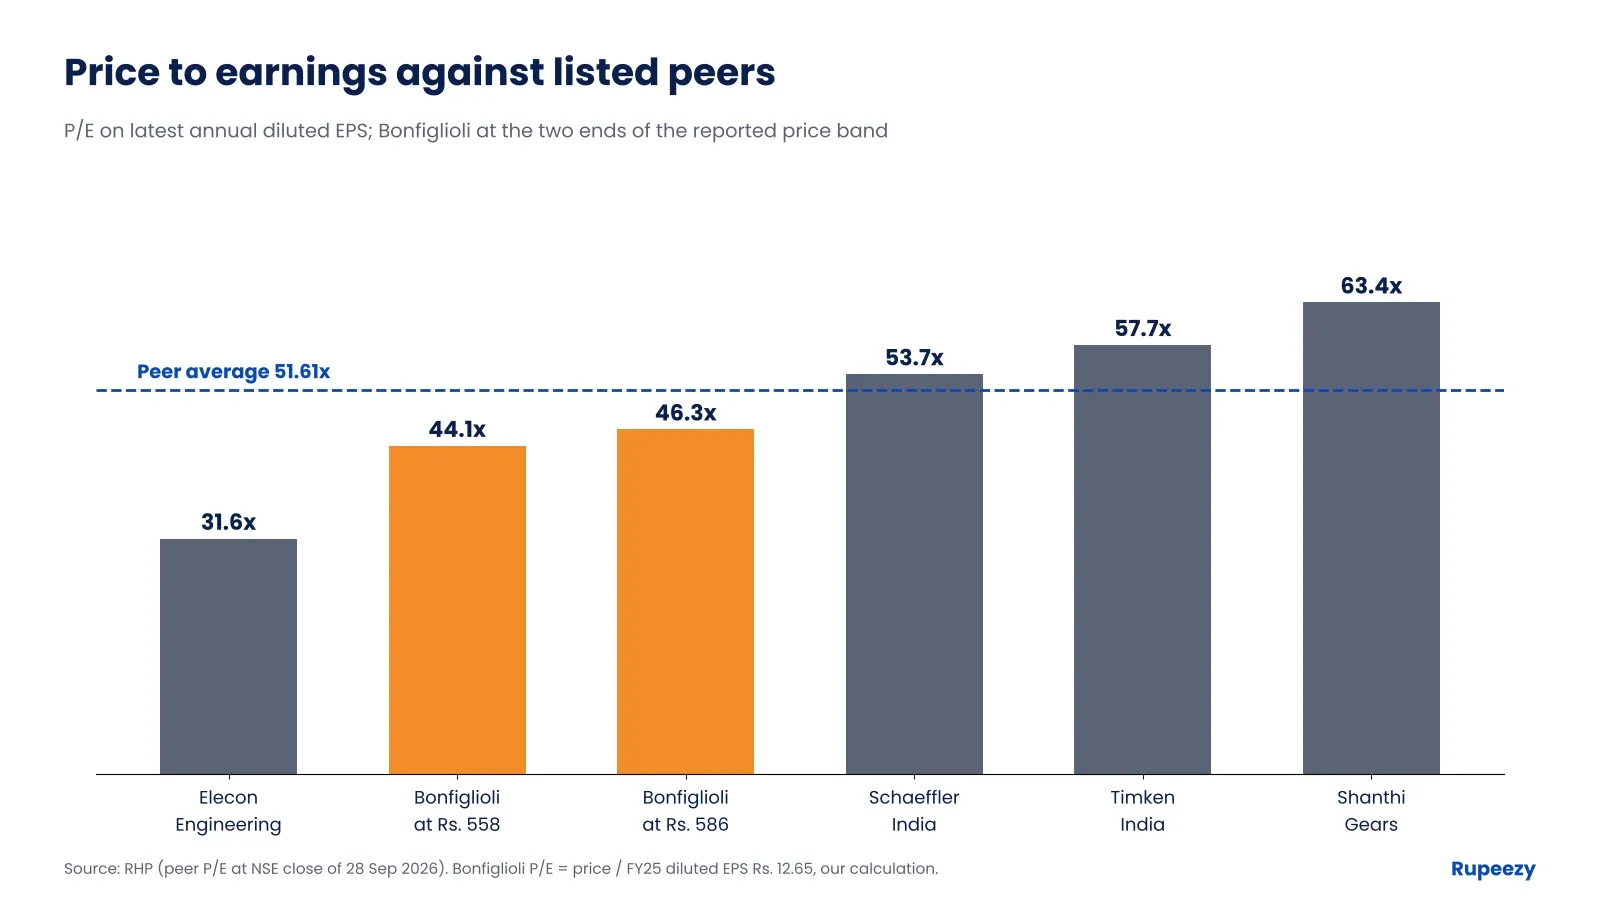
The RHP lists the price-to-earnings (P/E) ratios of four listed peers, using their closing prices on 28 September 2026 and their latest annual diluted EPS. Using the reported band of Rs. 558 to Rs. 586 and Bonfiglioli's FY25 diluted EPS of Rs. 12.65, the IPO P/E comes to 44.1 to 46.3 (our calculation).
Company | P/E (latest annual diluted EPS) |
Elecon Engineering | 31.63 |
Bonfiglioli at Rs. 558 (our calculation) | 44.11 |
Bonfiglioli at Rs. 586 (our calculation) | 46.32 |
Schaeffler India | 53.74 |
Timken India | 57.66 |
Shanthi Gears | 63.39 |
Average of the four listed peers | 51.61 |
At the reported band the company is priced below the peer average and above Elecon, a large listed gearbox maker. A few other measures, all our calculations from the RHP and the reported band, give more context:
Measure | At Rs. 558 | At Rs. 586 |
Market value (18,79,95,834 shares) | About Rs. 10,490 crore | About Rs. 11,017 crore |
P/E on FY25 diluted EPS (Rs. 12.65) | 44.1 | 46.3 |
P/E on last twelve months to June 2026 (EPS about Rs. 14.44) | 38.6 | 40.6 |
Price to net asset value (Rs. 52.82 at Dec 2025) | 10.6 times | 11.1 times |
Enterprise value to FY25 EBITDA | 27.9 times | 29.3 times |
Peers are not identical. Elecon, Shanthi Gears and Timken report to March 2026 while Schaeffler and Bonfiglioli report to December 2025, and Schaeffler and Timken make bearings and car parts as well. On the RHP's own comparison for the latest full year, Bonfiglioli's EBITDA margin (18.41%) is below Elecon's (22.11%) and Shanthi Gears' (20.03%) and close to Schaeffler's (18.20%) and Timken's (18.18%), while its return on equity of 25.66% is higher than all four (14.28% to 20.21%). The grey market premium (GMP) is unofficial and is not a signal to rely on.
Strengths of the Bonfiglioli Transmissions IPO
Profitable and debt-free: Profit after tax of Rs. 237.87 crore in FY25, no borrowings and Rs. 139.38 crore of net cash at June 2026.
Margins moving up: EBITDA margin rose from 14.45% in FY23 to 18.41% in FY25 and 19.78% in the first half of 2026.
High returns: Return on equity of 25.66% and return on capital employed of 34.05% in FY25.
Leading positions: The company says it holds 25.0% of low and medium duty gear motors in India and 67.9% of Indian-made yaw and pitch drives (company-commissioned report).
Long relationships: All of its top 10 Industry and Automation customers and eight of its top 10 off-highway customers have worked with it for more than 10 years, and no customer gave more than 11.43% of FY25 revenue.
Funds its own growth: Capex is paid from operating cash, and capacity use has risen to 75.04%.
Retail quota: At least 35% of the net offer is reserved for retail investors.
Risks of the Bonfiglioli Transmissions IPO
Risk | What the RHP shows |
Dependence on the parent | Most products are made under a one-year, auto-renewing licence from Bonfiglioli S.p.A. that either side can end by notice before 31 December. The royalty is 6% of licensed sales. |
Related-party dealings | Related parties gave 15.59% of total income in FY25, and 24.83% of total expenses went to them. The company plans to take a lease on land at Talegaon from a group company. |
No money for the company | It is a 100% OFS, so the parent receives the entire amount and the company gets nothing for growth or debt. |
Rising working capital | The cash conversion cycle lengthened from 80 days in FY23 to 94 days in June 2026, and receivables were 20.8% higher than a year earlier against 17.9% first-half revenue growth (our calculation). |
Cyclical demand | Sales depend on factory investment, construction and wind projects. Wind alone is 31.53% of revenue and depends on a few turbine makers. |
Export and currency exposure | 27.51% of FY25 revenue came from customers outside India, 15.52% from the USA alone, and the company has foreign exchange exposure. |
Tax disputes | Six tax claims total Rs. 35.44 crore, with the indirect tax demand paid under protest. A GST notice dated 25 August 2026 alleges excess input tax credit of Rs. 31.69 crore; the company has challenged it in the Madras High Court. |
Audit and compliance notes | Auditors noted that audit trail features were not enabled on some accounting software in FY24 and FY25, backups were not kept on servers in India, and some statutory dues such as TDS were paid late. The company took 194 days to appoint a company secretary in 2024 and has applied to the RoC for adjudication. |
Untraceable records | Some early incorporation and allotment forms filed with the RoC cannot be found, though the company says no penalty or notice has resulted. |
Industry data is company-paid | Market share and size figures come from a Frost & Sullivan report that the company commissioned and paid for. |
Valuation | At about 44 to 46 times FY25 earnings and 11 times book value, the price already assumes growth continues. |
Bonfiglioli Transmissions IPO: Good or Bad?
There is no single answer. This table sets out what points each way.
Question | Points to good | Points to bad |
Growth | Revenue up 9.9% and 8.6% in the last two full years and 17.9% in the first half of 2026 | Growth rates are in single digits for full years and tied to cyclical industries |
Profit | Profit after tax up 62.2% in two years; EBITDA margin 18.41% in FY25 | EBITDA margin is still below Elecon and Shanthi Gears |
Cash | No debt, Rs. 139.38 crore of net cash and about 79% of profit converted to cash in FY25 | Cash conversion cycle lengthened from 80 to 94 days |
Customers | More than 930 direct OEM customers; the largest gave 11.43% of FY25 revenue | Wind is 31.53% of revenue and rests on a few turbine makers |
Parent | Global brand and technology from a group with 18 production sites | Brand and technology are licensed for 6% of sales, and either side can end the licence by notice |
Price | P/E of 44.1 to 46.3 is below the peer average of 51.61 | About 11 times book value and above Elecon's 31.63 |
Use of money | The company does not need new capital for its current plans | The company receives none of the roughly Rs. 2,500 crore |
Allotment | At least 35% of the net offer is for retail | Allotment still depends on how many people bid |
If you want a profitable, debt-free industrial company with a long customer list and are comfortable that the parent keeps control of the brand and technology, the numbers give you something to work with. If you are uncomfortable that the only seller is the licensor, or you want the company itself to raise money for growth, this issue does not offer that. Only you can decide which matters more.
Questions to Settle Before You Bid
Are you comfortable that the licence for most of the company's products can be ended by notice before each 31 December?
Does paying about 44 to 46 times FY25 earnings make sense when full-year revenue growth has been in single digits?
Have you read the RHP's risk factors on related-party dealings, the GST notice and the auditors' notes?
How much of your portfolio would one lot at Rs. 14,650, or 13 lots at Rs. 1,90,450, be, and can you accept a loss on it?
Have you confirmed the final price band and lot size on the exchange websites?
How to Apply for Bonfiglioli Transmissions IPO on Rupeezy
If you decide to bid, you can apply through Rupeezy. Rupeezy's IPO page states "Zero fees on IPOs. Free account opening," so there is no charge for applying. That is a fact about our pricing, not a reason to bid. Rupeezy is a stockbroker and earns from other services if you become a client, which has no bearing on the analysis above.
Open a demat account. Open a free demat account with Rupeezy and finish the online KYC.
Keep a UPI ID ready. It must be linked to the bank account that holds your funds.
Go to the IPO section. Log in, open the IPO page and select Bonfiglioli Transmissions. Bidding runs from 15 to 19 October 2026; check the live window in the app.
Choose your bid. Pick the number of lots (1 to 13 for retail investors) and a price within the band, or bid at the cut-off price.
Approve the UPI mandate. The amount is blocked in your account, not debited, until shares are allotted.
Track allotment. Check it on the Rupeezy IPO allotment status page, the MUFG Intime website, BSE or NSE once the allotment date is announced.
New to this? Our step-by-step guide to applying for an IPO online covers the process.
Apply for Bonfiglioli Transmissions IPO | Open a free demat account
Frequently Asked Questions
Is the Bonfiglioli Transmissions IPO good or bad?
The RHP shows profit after tax of Rs. 237.87 crore in FY25, EBITDA margin of 18.41%, no borrowings and a P/E of about 44 to 46 at the reported band, below the peer average of 51.61. It also shows a 6% royalty to the parent, 15.59% of income from related parties and no money going to the company. It suits investors who accept a parent-controlled licence for steady industrial earnings; it does not suit those who want the company to raise growth capital. This is information, not a recommendation.
What is the Bonfiglioli Transmissions IPO price band and lot size?
Media reports of the company's announcement give a price band of Rs. 558 to Rs. 586 per share and a lot size of 25 shares, so the minimum bid is Rs. 14,650 at the upper band. The RHP leaves these blank, so confirm them on the exchange websites before you bid.
When does the Bonfiglioli Transmissions IPO open and close?
The RHP gives anchor bidding on 14 October 2026, with the public issue open from 15 October to 19 October 2026. The UPI mandate cut-off is 5:00 pm on 19 October. Allotment and listing dates follow the exchange timetable.
How big is the Bonfiglioli Transmissions IPO?
It is a 100% offer for sale of up to 4,32,39,042 shares, about 23.0% of the company, worth roughly Rs. 2,413 crore to Rs. 2,534 crore across the reported price band (our calculation). There is no fresh issue, so the company receives none of the money.
Who is selling shares in the Bonfiglioli Transmissions IPO?
Only Bonfiglioli S.p.A., the Italian parent that owns 100% of the company. It would hold about 77.0% after the offer (our calculation).
Is Bonfiglioli Transmissions profitable?
Yes. Restated profit after tax from continuing operations was Rs. 146.67 crore in FY23, Rs. 191.60 crore in FY24 and Rs. 237.87 crore in FY25, and Rs. 148.58 crore in the six months to June 2026. The company had net cash of Rs. 139.38 crore at June 2026.
How much can a retail investor bid for in the Bonfiglioli Transmissions IPO?
A retail investor can bid for up to 13 lots, which is 325 shares or Rs. 1,90,450 at Rs. 586, because the retail limit is Rs. 2 lakh. At least 35% of the net offer is reserved for retail investors.
How do I apply for the Bonfiglioli Transmissions IPO on Rupeezy?
Open a demat account with Rupeezy, log in, go to the IPO section, select Bonfiglioli Transmissions, choose your lots and price, and approve the UPI mandate. Rupeezy states zero fees on IPOs and free account opening.
Sources
Bonfiglioli Transmissions Limited, Red Herring Prospectus dated 9 October 2026, published by the company: bonfiglioli.com. Source for financials, cash flow, KPIs, peer P/E ratios, ownership, related-party and royalty disclosures, risk factors, litigation and offer structure.
Frost & Sullivan industry report dated 28 September 2026, as cited in the RHP. Commissioned and paid for by the company.
Price band and lot size: media reports of the company's announcement (for example Business Today, 12 October 2026), because the RHP leaves them blank. Confirm against the final price band advertisement.
All data is as of 14 October 2026. Figures in Rs. crore are converted from the RHP's Rs. million figures and rounded. Issue size, share of company sold and held, market value, P/E at the band, price to book, enterprise value to EBITDA, growth rates, cash left after capex, dividend and buyback totals and retail bid limits are our calculations from RHP data and the reported price band.
Santhosh is a Research Analyst at Rupeezy who transforms complex market data into actionable insights for investors. With five years of financial industry experience and an MBA in Finance from Jain University, he specializes in evaluating stock market dynamics, mutual fund performance, and ETF trends. Driven by a deep passion for business analysis, Santhosh focuses heavily on company fundamentals to help readers make informed, data-backed financial decisions.
Did you like this blog?
Be the first to like this blog.
Disclaimer
Investments in the securities market are subject to market risks. Read all the related documents carefully before investing. Rupeezy (SEBI RA Registration: INH000013332) provides this content for informational purposes; any securities quoted are for educational display and not as a recommendation. All charts and graphs are based on independent research and reliable sources for the period mentioned within the specific data set. Sometimes we take graphs from external sources. This communication does not promise or assure any fixed, guaranteed, or indicative returns to any client. For our complete registered office address, Member ID, and full SEBI registration details, please refer to our official website.
The content on this blog is for educational purposes only and should not be considered investment advice. While we strive for accuracy, some information may contain errors or delays in updates.
Mentions of stocks or investment products are solely for informational purposes and do not constitute recommendations. Investors should conduct their own research before making any decisions.
Investing in financial markets are subject to market risks, and past performance does not guarantee future results. It is advisable to consult a qualified financial professional, review official documents, and verify information independently before making investment decisions.

All Category